This abstract class defines common interfaces and types for a generic Kalman filter. More...
#include <kalman_filter.h>
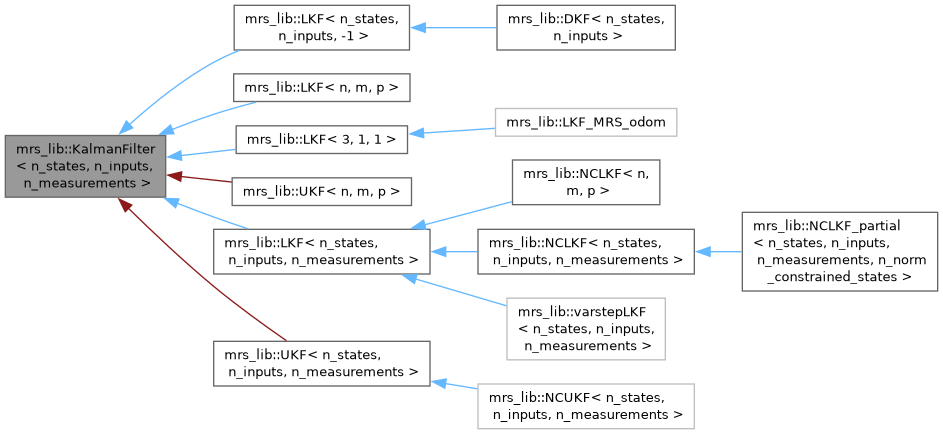
Classes | |
| struct | statecov_t |
| Helper struct for passing around the state and its covariance in one variable. More... | |
Public Types | |
| typedef Eigen::Matrix< double, n, 1 > | x_t |
State vector type  | |
| typedef Eigen::Matrix< double, m, 1 > | u_t |
Input vector type  | |
| typedef Eigen::Matrix< double, p, 1 > | z_t |
Measurement vector type  | |
| typedef Eigen::Matrix< double, n, n > | P_t |
State uncertainty covariance matrix type  | |
| typedef Eigen::Matrix< double, p, p > | R_t |
Measurement noise covariance matrix type  | |
| typedef Eigen::Matrix< double, n, n > | Q_t |
| Process noise covariance matrix type | |
Public Member Functions | |
| virtual statecov_t | correct (const statecov_t &sc, const z_t &z, const R_t &R) const =0 |
| Applies the correction (update, measurement, data) step of the Kalman filter. | |
| virtual statecov_t | predict (const statecov_t &sc, const u_t &u, const Q_t &Q, double dt) const =0 |
| Applies the prediction (time) step of the Kalman filter. | |
Detailed Description
class mrs_lib::KalmanFilter< n_states, n_inputs, n_measurements >
This abstract class defines common interfaces and types for a generic Kalman filter.
- Template Parameters
-
n_states number of states of the system (length of the 
n_inputs number of inputs of the system (length of the 
n_measurements number of measurements of the system (length of the 


Member Function Documentation
◆ correct()
|
pure virtual |
Applies the correction (update, measurement, data) step of the Kalman filter.
This method applies the correction step to the state and covariance passed in sc using the measurement z and measurement noise R. An optional parameter param may be used by some implementations, but it is usually ignored. The updated state and covariance after the correction step is returned.
- Parameters
-
sc The state and covariance to which the correction step is to be applied. z The measurement vector to be used for correction. R The measurement noise covariance matrix to be used for correction.
- Returns
- The state and covariance after the correction update.
◆ predict()
|
pure virtual |
Applies the prediction (time) step of the Kalman filter.
This method applies the prediction step to the state and covariance passed in sc using the input u and process noise Q. The state and covariance are updated by dt into the future, if applicable to the implementation. An optional parameter param may be used by some implementations, but it is usually ignored. The updated state and covariance after the prediction step is returned.
- Parameters
-
sc The state and covariance to which the prediction step is to be applied. u The input vector to be used for prediction. Q The process noise covariance matrix to be used for prediction. dt The time step for the prediction update (the state and covariance will be predicted by dt into the future).
- Returns
- The state and covariance after the prediction step.
The documentation for this class was generated from the following file:
- /home/runner/work/mrs_lib/mrs_lib/include/mrs_lib/kalman_filter.h
